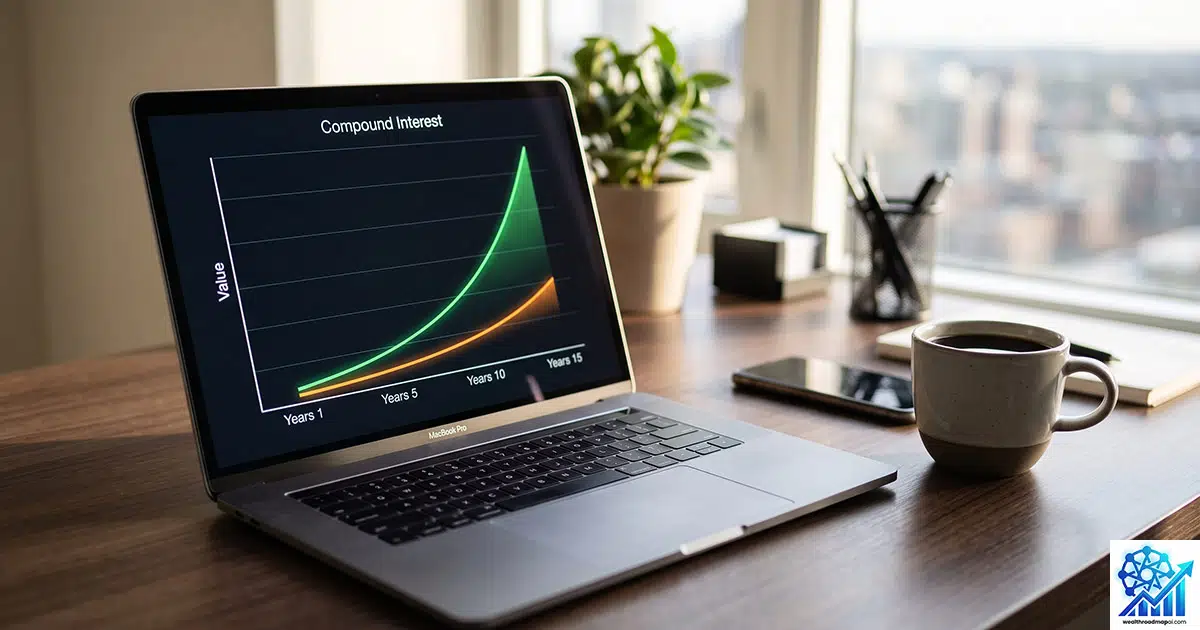
This site is a compound interest calculator plus a few U.S. investing guides. It is not a crystal ball. If you treat an 8% line as a promise, you will oversave in your head and undersave in real life. The Investor.gov glossary on compound interest matches the idea behind the formula.
Here is how to use the four inputs, how to read contributions vs growth, and what the tool will never know about your 401(k) match or tax bracket.
What the formula actually does
Compound interest means you earn a return on both the original money and on returns already earned. The calculator compounds monthly and adds contributions at the end of each month. If the annual rate is 0%, it correctly falls back to starting amount + monthly × 12 × years.
Numbers stay in your browser. Nothing you type is sent to a server. See About.
The four levers
- Starting amount: cash or invested balance you already have. Type a real number; the slider is just a shortcut.
- Monthly contribution: what you can keep doing in a recession, not your best month. Dollar-cost averaging only works if the transfer actually happens.
- Years: use working years left, not a round 10 because it looks neat. Compounding is back-loaded.
- Expected return: default 8% is a planning rate near long-run U.S. large-cap history, not next year’s S&P 500. Read why 8% is a planning number.
Read “you put in” before you read the big blue number
Example: $10,000 start, $500 a month, 8%, 10 years. You deposit $70,000. The formula projects about $113,700, so estimated growth is about $43,700. That split is more honest than a single headline total.
Turn on “today’s dollars” if you are aiming at a 4% rule nest egg. A future $1 million is not a 2026 $1 million.
What-ifs that are worth running
- Same savings at 5% — if the plan dies, save more or work longer; do not raise the return slider.
- $50 extra per month over 25 years — usually more powerful than arguing about 8% vs 8.5%.
- Two extra working years — often cheaper than a more aggressive portfolio.
The calculator does not model employer match, Roth vs traditional tax, or required minimum distributions. For account choice, use 401(k) vs Roth IRA. For cash vs stocks, use emergency fund vs investing.
Then do the unglamorous part
- Enter honest numbers on the calculator.
- Automate the contribution at Fidelity, Vanguard, Schwab, or payroll 401(k).
- Leave the fund alone when headlines get loud. The formula assumes you do not sell.